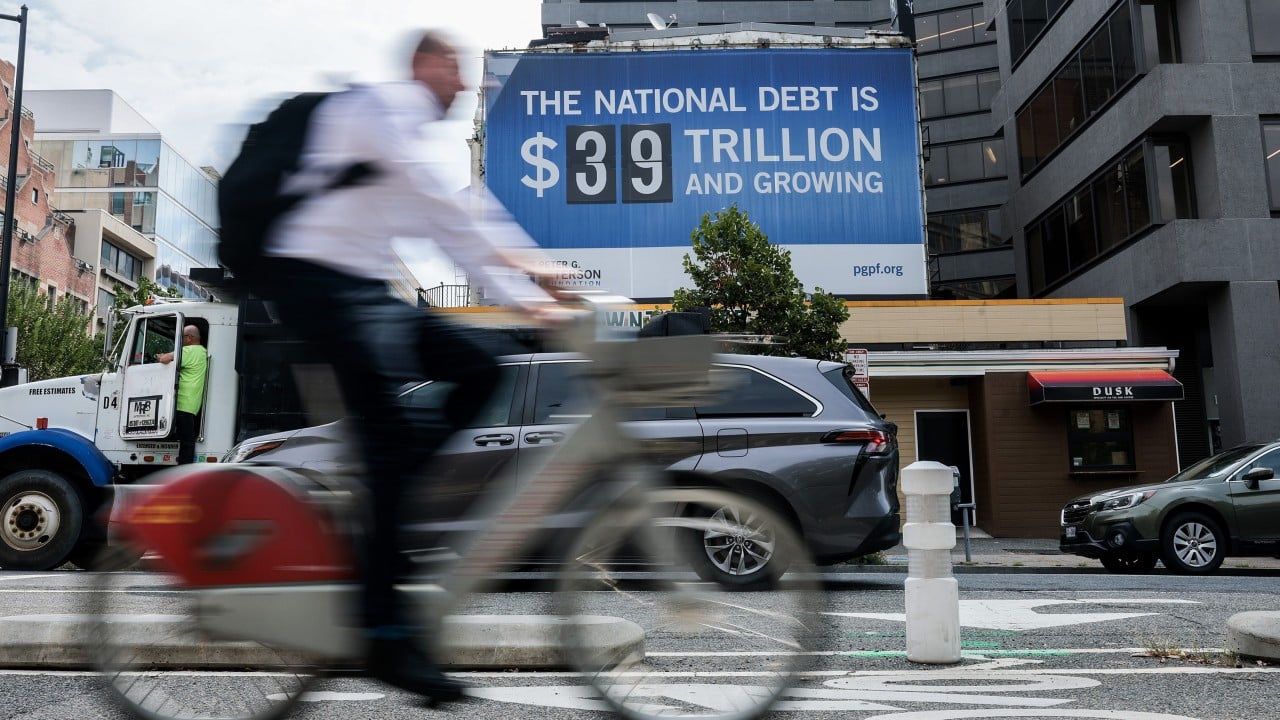
The 2026 midterm elections handed Democrats control of both chambers of Congress, setting up a collision with President Donald Trump over the $41.1 trillion statutory debt ceiling that threatens to surpass the market trauma of 2011. Unlike fifteen years ago, when the Tea Party used the borrowing cap to demand austerity from a Democratic president, the script has inverted. Now, a Democratic majority holds the sole legislative choke point capable of reversing Republican cuts to Medicaid and food assistance, while global bond markets watch with far less patience and significantly higher interest rates.
Washington has a short memory for fiscal brinkmanship, yet Wall Street remembers August 2011 down to the basis point. That summer, Standard & Poor’s stripped the United States of its triple-A credit rating for the first time in history after lawmakers came within 72 hours of a technical default. Equity markets plunged, consumer confidence cratered, and taxpayers absorbed billions in elevated borrowing costs. Analysts looking at the post-midterm chessboard warn that the coming standoff carries structural hazards that make 2011 look like a dress rehearsal.
Why the 2027 Calendar Locks Both Sides In
The arithmetic leaves zero room for wishful thinking. Congress last raised the debt limit in July 2025, adding $5 trillion through a party-line reconciliation bill to reach the current $41.1 trillion ceiling. By late October 2026, debt subject to the limit had already climbed to $40.93 trillion, leaving less than $800 billion in remaining headroom.
According to projections released in November 2026 by the Bipartisan Policy Center, the Treasury Department will hit that wall in February or March 2027. Once the cap is breached, Treasury Secretary Scott Bessent will trigger so-called extraordinary measures—accounting maneuvers that suspend investments in federal employee retirement funds and pause rollovers of certain intragovernmental securities to free up cash. Those stopgaps will buy the government roughly six to nine months, pushing the true X-date—the day the United States runs out of cash to pay its legal obligations—into the autumn of 2027, likely between August and November.
There is a narrow exit ramp right now. Republicans still hold the gavel during the lame-duck session before the new Congress convenes in January 2027. GOP leaders could theoretically use budget reconciliation to lift or suspend the limit before handing over the keys. Yet few on Capitol Hill expect that to happen. Rank-and-file Republicans have spent years railing against debt increases, and passing another hike on their way out the door would spark an internal revolt while handing Democrats a clean slate.
Assuming the lame-duck window closes untouched, the 120th Congress will inherit a ticking clock.
The Reversed Hostage Dynamic
Every major debt ceiling crisis since 1995 has followed a familiar script. Fiscal conservatives in Congress threaten to block a borrowing increase unless a Democratic White House agrees to spending cuts. The 2026 midterms flipped that dynamic on its head.
Because the GOP passed its major tax and spending package—the One Big Beautiful Bill Act—on a partisan vote in 2025, Democrats spent two years locked out of legislative power. Winning both the House and the Senate gives them a veto over presidential appointments and future appropriations, but it does not let them repeal existing law over a Trump veto. The debt limit is the one must-pass vehicle where the White House cannot simply wait Congress out.
Democratic strategists and tax policy analysts have already mapped out the ransom note. Expect congressional leaders to demand the restoration of Medicaid and SNAP funding trimmed in the 2025 reconciliation law, alongside the revival of expanded Affordable Care Act premium tax credits that expired at the end of 2025.
This creates a far more volatile negotiation than 2011 for one simple reason. In 2011, both Barack Obama and John Boehner wanted a deficit-reduction deal; they merely fought over the mix of tax hikes and entitlement cuts. In 2027, neither side wants austerity. The Trump administration is pushing for a $500 billion boost in defense spending for fiscal 2027 while defending its tax cuts, whereas Democrats want to restore domestic social spending. When both parties demand policies that expand the deficit as the price for raising the borrowing cap, the traditional off-ramp of a "grand bargain" vanishes.
What Changed in the Bond Market Since 2011
Politicians often assume they can play chicken right up to the final hour because the bond market always rallies once a deal is signed. That assumption rests on 2011 math that no longer exists.
Fifteen years ago, the U.S. national debt stood at $14.3 trillion, roughly 95% of gross domestic product. The Federal Reserve held benchmark interest rates near zero, and 10-year Treasury yields hovered below 3% even during the worst weeks of the standoff. Foreign central banks, led by China and Japan, eagerly soaked up U.S. debt regardless of Washington dysfunction.
Look at the ledger today. Total federal debt has crossed $40 trillion, pushing the debt-to-GDP ratio past 120%. Net interest payments alone jumped 8% in fiscal 2026, adding $81 billion in annual servicing costs as older, low-rate bonds matured and rolled over into yields between 4% and 5%. Meanwhile, Fitch Ratings already downgraded the U.S. from AAA to AA+ in 2023, and Moody’s stripped its top rating shortly after, leaving Washington with zero AAA cushions left to absorb a shock.
To keep interest costs manageable, the Treasury has leaned heavily on short-term Treasury bills rather than long-dated bonds. That strategy works well in calm waters, yet it leaves the government perpetually refinancing trillions of dollars every few weeks. If a 2027 standoff sparks even a brief buyers' strike in the T-bill market, the resulting spike in short-term yields will feed directly into the federal deficit within months, creating a self-reinforcing fiscal spiral.
The Forgotten Trap of Treasury Cash Management
Most coverage of the debt ceiling treats the X-date as a single cliff, but institutional traders know the damage begins weeks earlier through a technical distortion in Treasury cash balances.
Under normal operations, the Treasury maintains a cash buffer—the Treasury General Account—of roughly $800 billion to $1 trillion to ensure smooth daily payments. When the debt limit binds in early 2027, the department cannot issue net new debt to replenish that account. Over the spring and summer, Bessent will be forced to drain that cash cushion down toward zero while relying on extraordinary measures.
Draining hundreds of billions of dollars from the Treasury General Account floods the banking system with artificial liquidity. Once Congress finally cuts a deal and raises the ceiling, the Treasury has to reverse the process immediately, dumping a massive wave of T-bills onto the market to rebuild its cash buffer. That sudden issuance sucks liquidity out of commercial banks and money market funds overnight, tightening financial conditions just as investors try to recover from weeks of political chaos.
Consider a hypothetical scenario based on recent market mechanics. Suppose Congress waits until October 2027 to lift the cap, forcing Treasury to rebuild a $900 billion cash balance in under sixty days. Commercial banks holding reserves at the Federal Reserve would suddenly pull cash out of corporate lending and repo markets to buy high-yielding Treasury bills. Even without a single missed coupon payment, the mechanical aftermath of the standoff could trigger a credit crunch across regional banks and corporate debt markets.
Why The Usual Escape Hatches Are Weak
Whenever a debt limit crisis looms, pundits dust off three theoretical workarounds: the 14th Amendment, the trillion-dollar platinum coin, and payment prioritization. None of them offers a clean escape in 2027.
Invoking Section 4 of the 14th Amendment—which states that the validity of the public debt shall not be questioned—would allow the White House to ignore the statutory cap and keep borrowing. Yet doing so would instantly trigger a constitutional lawsuit from Congress. While the Supreme Court deliberated, investors would be asked to buy "unconstitutional" Treasury bonds whose legal validity hung in limbo. Those bonds would trade at a steep discount to existing Treasuries, fracturing the world's benchmark risk-free asset into two tiers overnight.
Minting a $1 trillion platinum coin under an obscure numismatic statute and depositing it at the Federal Reserve faces similar resistance. Federal Reserve officials have repeatedly signaled they have no interest in acting as a partisan referee by accepting a gimmick coin to finance fiscal deficits, and the resulting legal fight would spook currency markets just as badly as a congressional deadlock.
Payment prioritization—where the Treasury uses incoming tax revenue to pay bondholders first while delaying Social Security checks, military salaries, and contractor bills—is technically feasible on paper. In practice, Treasury payment systems process millions of automated disbursements daily and were never built to sort recipients by political priority. Even if engineers could separate bond coupons from Medicare reimbursements, halting domestic payments to protect Wall Street bondholders would detonate a political firestorm within 48 hours, effectively triggering a severe recession through an immediate collapse in consumer spending.
The Counterargument That Wall Street Is Missing
Despite the bleak arithmetic, a strong case exists that Washington could still avoid a catastrophe—not out of newfound statesmanship, but out of mutual self-preservation.
President Trump has publicly stated in the past that he dislikes the debt ceiling because it creates unnecessary economic risk, even floating the idea of abolishing the limit altogether during his second-term transition. A growing faction of Senate Democrats shares that view, recognizing that the debt limit serves primarily as an asymmetric weapon against whichever party occupies the White House. If Trump decides that a stock market crash in late 2027 would ruin his economic legacy ahead of the 2028 presidential race, he could bypass hardliners in both parties and cut a direct deal with Senate Democratic leadership to suspend the cap through 2029.
Furthermore, tax receipts in fiscal 2026 came in roughly $80 billion above projections thanks to steady employment, giving Treasury slightly more breathing room than pessimists feared. If April 2027 tax collections surprise to the upside, the X-date could drift into November or December 2027, giving negotiators extra weeks to find a face-saving compromise on healthcare subsidies and defense appropriations.
Still, betting a $30 trillion economy on the hope that two bitter political rivals will suddenly choose pragmatism is a dangerous wager.
What Investors and Households Should Watch
The warning signs will not appear first on cable news; they will show up in the credit default swap (CDS) market and the Treasury bill yield curve.
In a normal market, U.S. sovereign credit default swaps—essentially insurance policies against a government default—trade for pennies. During the 2011 and 2023 standoffs, one-year U.S. CDS spreads spiked above 170 basis points, pricing in a higher risk of default than several emerging-market economies. Simultaneously, yields on Treasury bills maturing right around the projected X-date will develop a sharp "kink," trading 100 to 200 basis points higher than bills maturing just two weeks earlier as money market funds dump any security that might be caught in a delayed payment window.
For institutional desks and corporate treasurers, the playbook is already shifting toward holding cash in overnight reverse repo facilities or Treasury bills maturing strictly before July 2027. For ordinary households, the immediate risk is not a permanent loss on government bonds, but a sharp spike in mortgage rates, auto loans, and credit card APRs—all of which price off the 10-year Treasury yield. When Washington turns the full faith and credit of the United States into a negotiating chip, Main Street pays the interest rate penalty long before a single check bounces.
Watch the December 11, 2026 government funding deadline first. If the outgoing Congress cannot even pass a routine spending extension without a shutdown threat, treat that failure as the opening bell for a 2027 debt ceiling crisis that neither party knows how to stop.