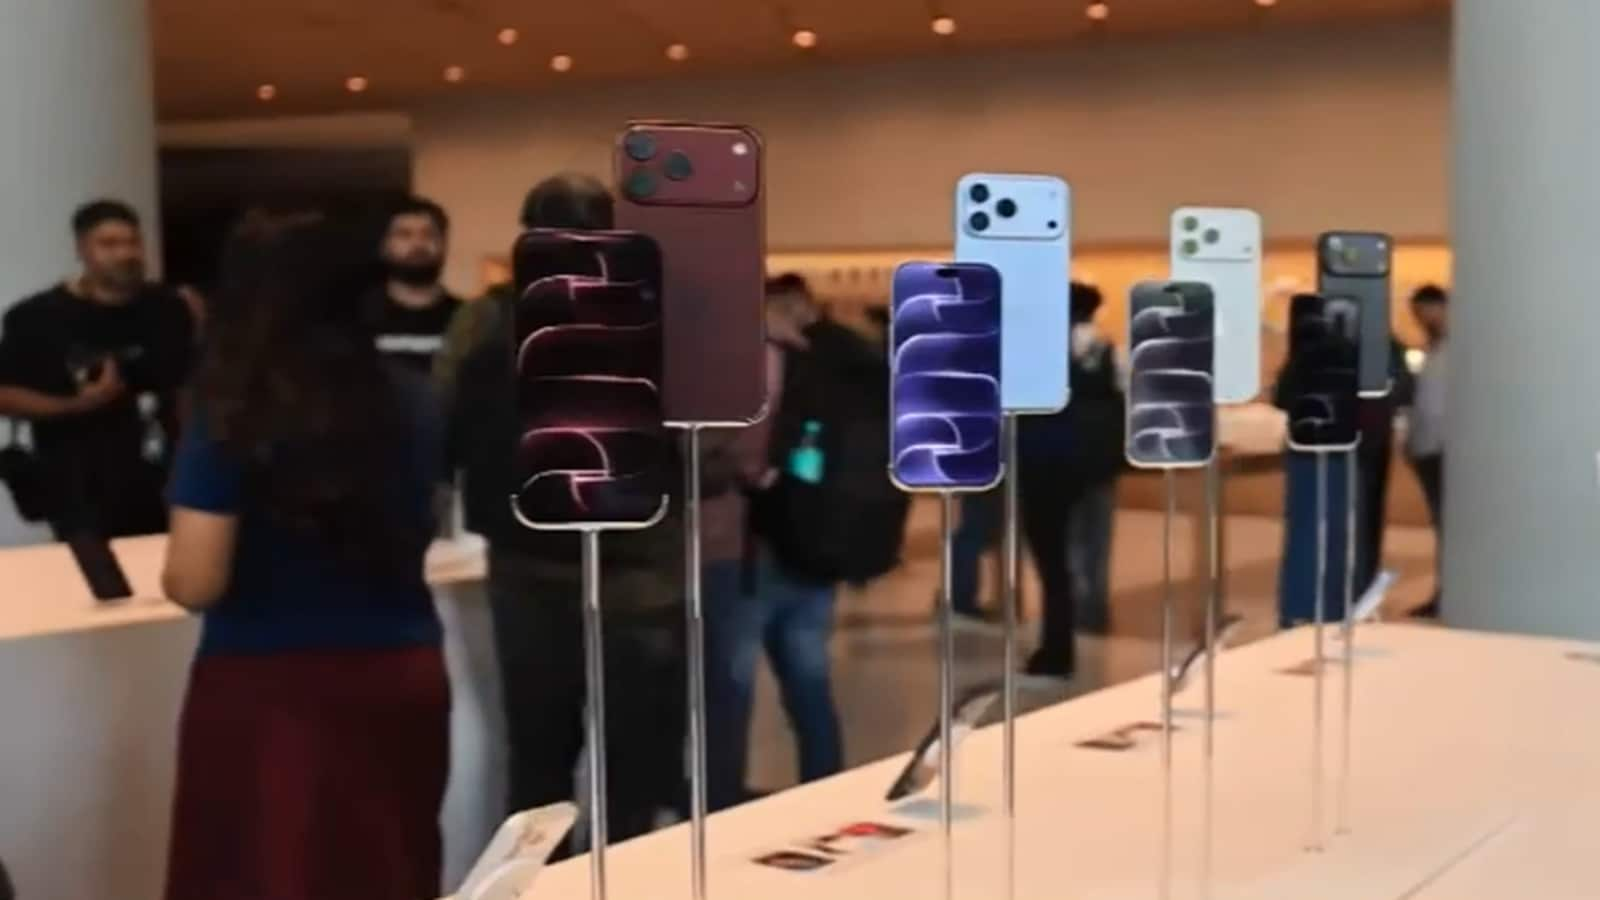
When a dominant hardware manufacturer reduces production allocations by double-digit percentages during a major product cycle, the adjustment signals an acute structural inflection point rather than a routine supply chain fluctuation. Reports indicating a fifteen percent downward revision in component orders for upcoming high-tier mobile devices expose the collision between ascending retail price ceilings and diminishing marginal utility for consumers. Dissecting this adjustment requires moving past superficial supply chain noise to examine the underlying mechanics of pricing power, replacement cycles, and consumer utility thresholds.
The Pricing Power Boundary And Consumer Substitution
Hardware manufacturers operate within a defined boundary of pricing elasticity. For years, the premium mobile sector relied on a strategy of continuous average selling price expansion. By introducing incremental hardware iterations packaged with elevated price tags, brands tested the upper limits of consumer willingness to pay.
However, smartphones have crossed from discretionary luxury goods into foundational utility infrastructure. As prices migrate past traditional psychological barriers, the cost-benefit calculus shifts for the end buyer. When a device requires a four-figure capital outlay, the performance delta between generational upgrades narrows significantly in the perception of the market.
This creates a substitution effect operating across multiple vectors:
- Intra-brand retention: Consumers retain existing hardware for longer durations, extending the average replacement cycle from two years toward three or four years.
- Inter-category reallocation: Disposable income shifts away from consumer electronics toward experiential spending or essential goods impacted by broader macroeconomic pressures.
- Alternative tier migration: Buyers gravitate toward lower-priced standard models or certified refurbished inventory, compressing the margin profile of the manufacturer.
A fifteen percent reduction in component volume reflects a direct mathematical response to this demand compression. When sell-through rates at retail fail to absorb forecasted units, channel inventory accumulates. To prevent margin erosion via aggressive discounting later, supply chain inputs must contract immediately.
The Cost Structure Of Incremental Innovation
Understanding why price increases become mandatory even as demand softens requires examining the cost function of advanced semiconductor manufacturing and materials sourcing.
As silicon nodes shrink and fabrication complexity increases, the cost per transistor ceases to follow traditional historical deflation curves. Securing leading-edge processing nodes requires massive upfront capital expenditure commitments with semiconductor foundries. Consequently, the unit cost of core processing components rises with every generation.
At the same time, physical constraints limit radical exterior redesigns. Consumers notice marginal changes to display bezels, camera array configurations, or minor weight reductions far less than they notice a substantial jump in the purchase price. When input costs escalate due to advanced manufacturing demands, manufacturers face a binary choice: absorb the margin contraction or pass the cost to the consumer.
Passing the cost forward maintains short-term profitability metrics per unit sold but accelerates demand destruction among price-sensitive segments of the premium demographic. This dynamic creates an inverse feedback loop where higher prices depress volume, which in turn reduces economies of scale across manufacturing partners, driving up baseline unit costs still further.
The Saturation Mechanics Of The Replacement Cycle
The primary structural headwind facing the premium mobile market is not cyclical economic volatility, but structural market maturity. High-tier smartphones achieved feature parity and performance abundance several years ago.
Consider the utility curve of processing power and camera fidelity. For the average user, a device manufactured three years ago handles communication, media consumption, and productivity tasks without latency or functional limitation. The marginal utility of a faster neural engine or a slightly higher optical zoom factor approaches zero for a large portion of the installed base.
Without a paradigm-shifting functional catalyst—comparable to the transition from feature phones to touch-screen interfaces—replacement behavior reverts to a maintenance-driven model. Devices are replaced upon failure, battery degradation beyond functional thresholds, or accidental physical destruction.
When manufacturers attempt to artificially accelerate replacement through software support limitations or minor specification bumps, sophisticated consumers recognize the artificial obsolescence. The resulting extension of the replacement cycle structurally reduces the total addressable market size for new unit sales during any given fiscal year.
Strategic Capital Allocation In A Mature Hardware Ecosystem
Navigating an environment characterized by plateauing hardware demand and escalating input costs demands a fundamental shift in corporate strategy. Reliance on unit volume expansion through annual device iteration faces diminishing returns.
Market leaders must decouple revenue growth from unit sales velocity by aggressively expanding high-margin software and service ecosystems. Services create a recurring revenue annuity that mitigates the cyclical volatility inherent in hardware manufacturing. By embedding users deeper into proprietary software, cloud storage, financial services, and media subscriptions, the lifetime value of each customer increases independently of annual upgrade behavior.
Simultaneously, supply chain management must transition from rigid forecasting models to agile, demand-sensing architectures. Reducing component orders by fifteen percent is a reactive measure to correct inventory imbalances. The objective for mature hardware operations is to utilize real-time sell-through telemetry to adjust manufacturing output dynamically, eliminating the financial drag of excess component buffer stock.
Value proposition communication must also evolve. Marketing language that emphasizes micro-improvements in silicon architecture or incremental camera capabilities fails to justify premium price positioning to a saturated market. Strategic messaging must pivot toward tangible longevity, privacy architecture, and operational integration across an ecosystem, framing the hardware purchase as a long-term infrastructure investment rather than a disposable consumer good.
To stabilize margins without inducing further demand contraction, pricing strategies must incorporate tiered financing structures, trade-in valuation subsidies, and modular service bundles that lower the friction of the initial capital outlay. Restoring equilibrium to the premium hardware sector requires aligning retail pricing models with the actual, realized utility perceived by the modern consumer.