Money has a voice. In most households living on the razor's edge, that voice is a persistent, low-grade hum of anxiety. It sounds like the refrigerator compressor kicking on three times an hour, or the hollow echo of coins rolling around the bottom of a cup holder. It is the language of subtraction. Every purchase is a micro-calculation, a mental subtraction of future stability for present survival.
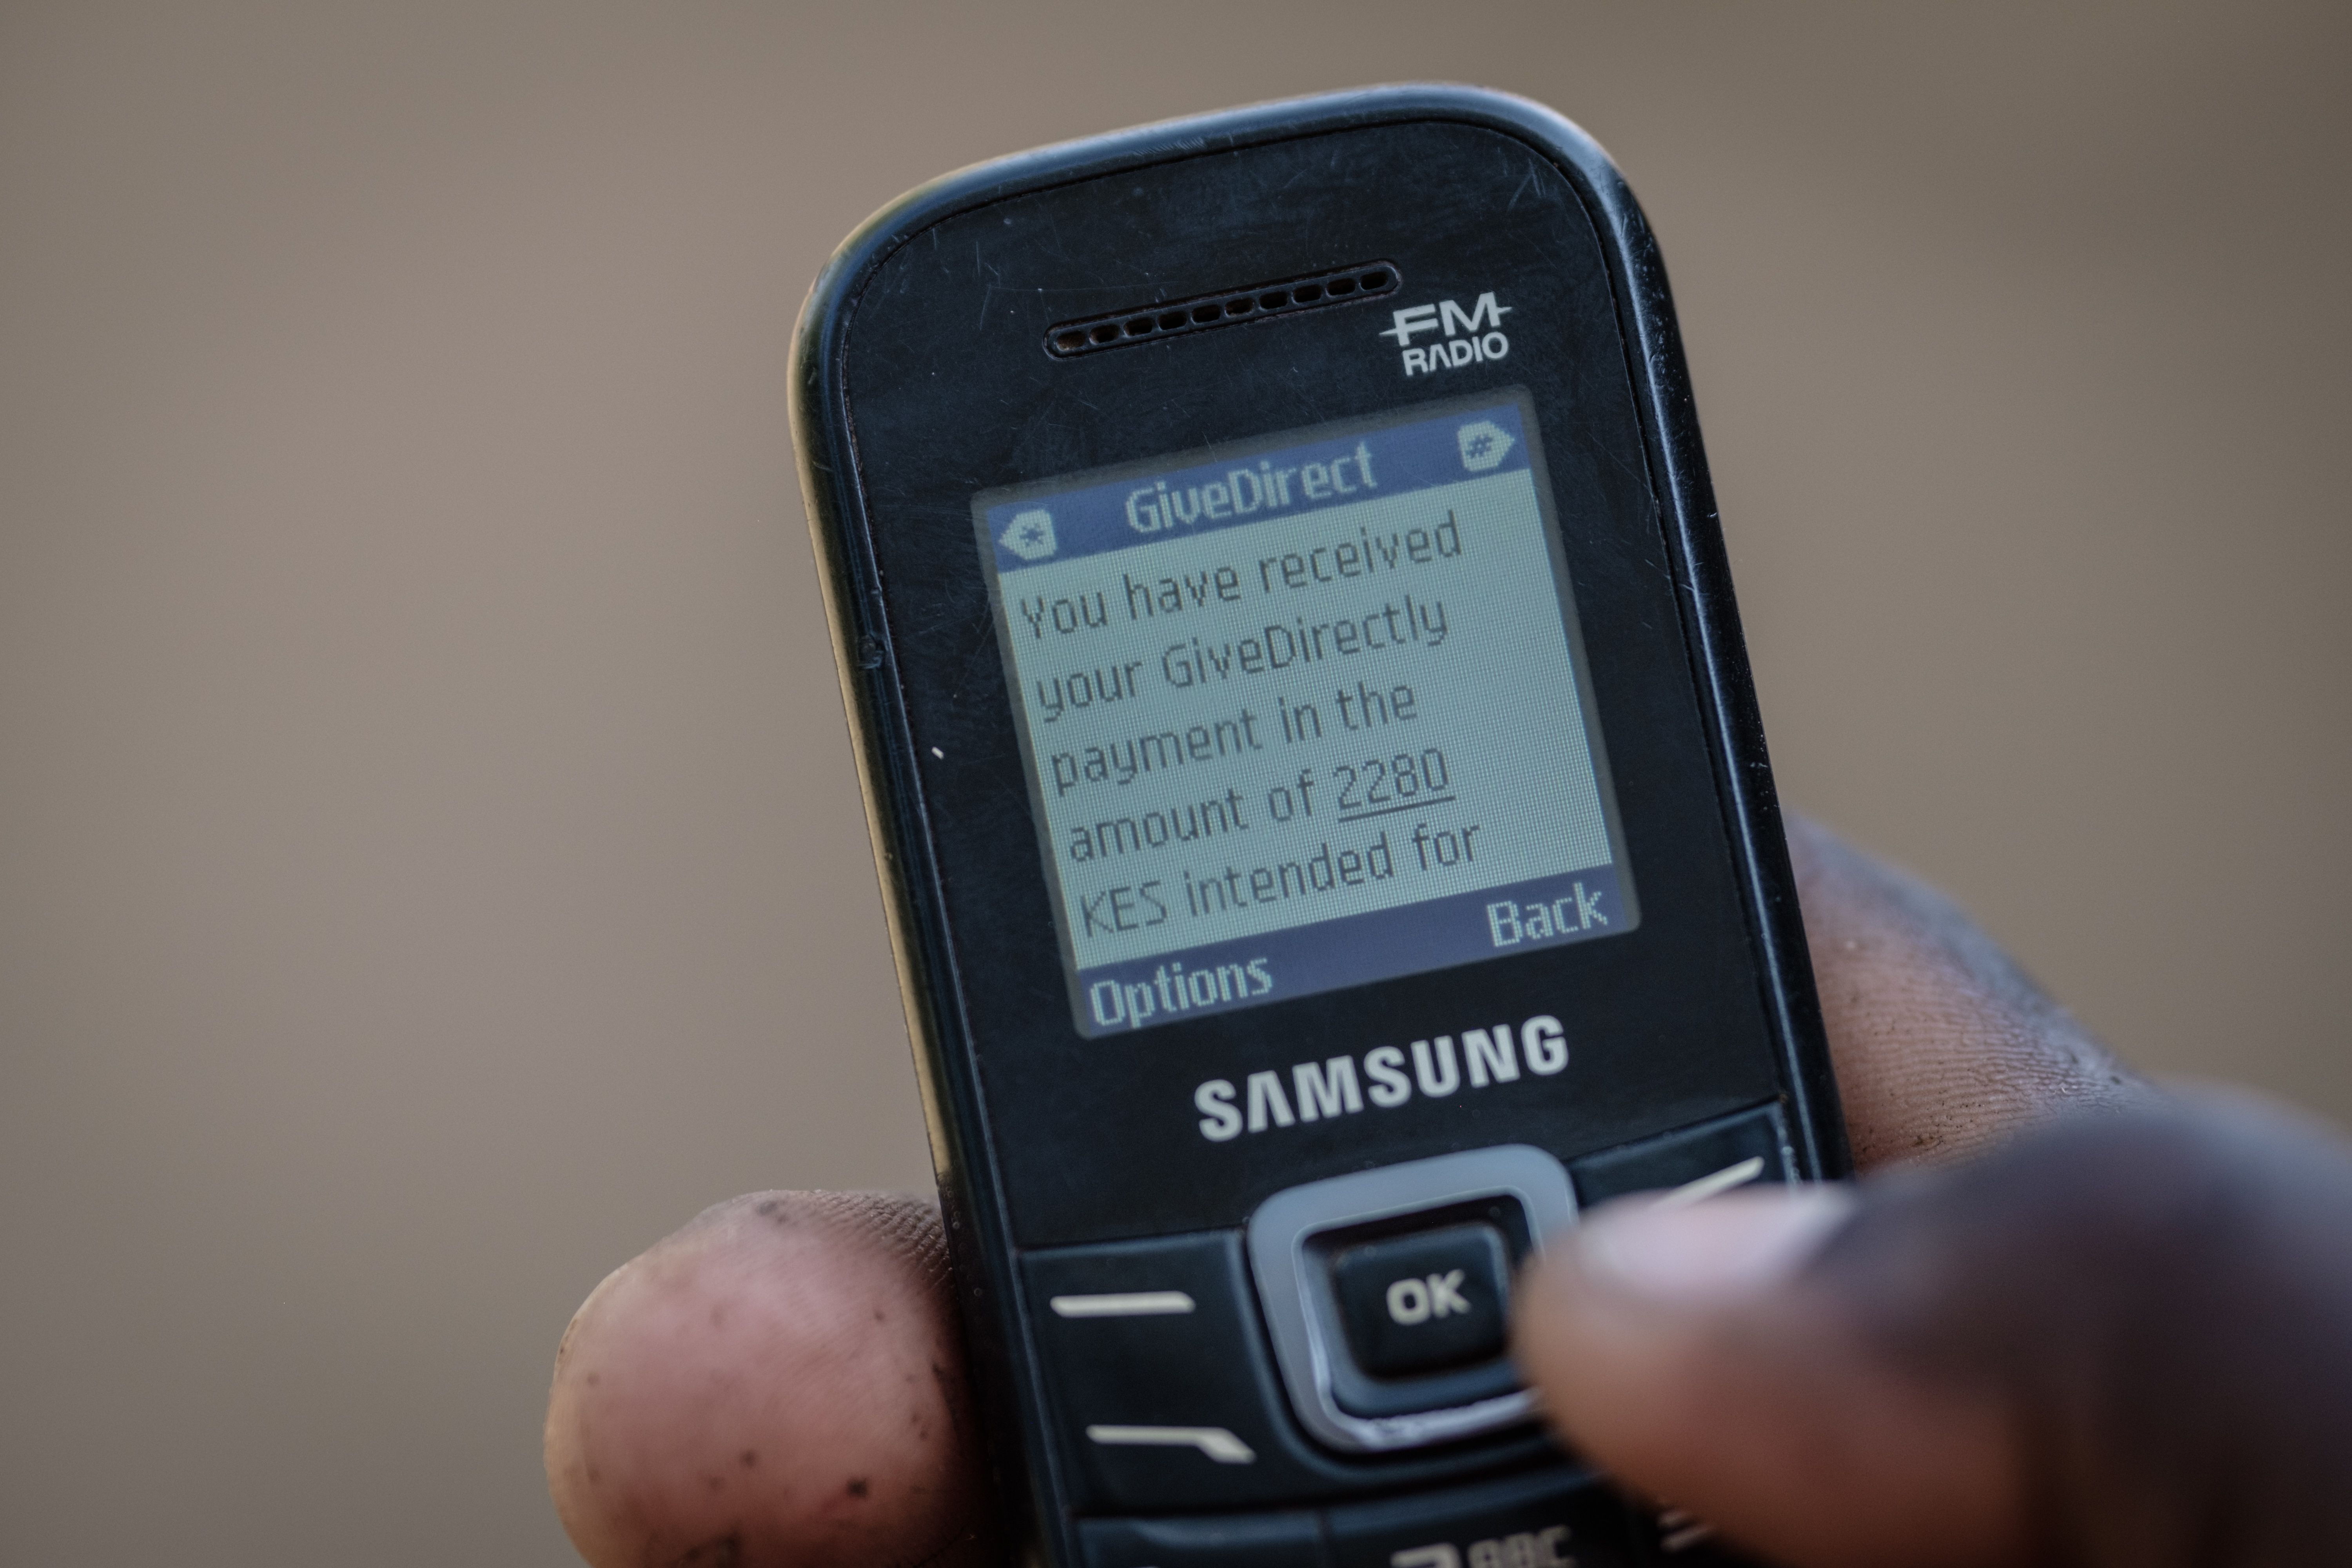
Now, imagine dropping an injection of hard cash into that quiet storm. Not a loan. Not a paycheck earned through sixty hours of bone-weary labor. Pure, unadulterated cash. But with a catch. It arrives accompanied by a binder, a spreadsheet, a blueprint dictated by someone who has never stared at a utility shut-off notice while wondering which credit card to sacrifice to the gods of minimum payments.
What happens when you hand struggling couples money and a strict spending plan?
The answer is not a neat, inspiring headline. It is a messy, deeply human friction between relief and control. The results are remarkably good, and quietly devastating.
Consider a hypothetical couple, Elena and Marcus. They live in a cramped apartment where the floorboards groan under the weight of three jobs between them. Marcus works logistics at a warehouse, lifting boxes until his lower back sings a dull ache into the night. Elena manages front-desk intake at a veterinary clinic, absorbing the grief of pet owners while calculating whether her tips will cover the cost of her daughter's inhaler refill. Their relationship is not broken by lack of love; it is eroded by the friction of perpetual deficit. Every conversation about the future is hijacked by the immediate tyranny of the bill pile.
When researchers or policymakers step into lives like theirs with cash transfer programs coupled with structured financial counseling, they are acting on a seductive economic theory. The theory states that poverty is primarily a liquidity problem combined with a knowledge gap. Give people cash to solve the immediate emergency, the logic goes, and give them a structured spending plan to ensure they do not squander it on fleeting dopamine hits. Fix the math, fix the life.
For a moment, it feels like magic.
When the initial cash injection clears, the physical posture of a household shifts. Shoulders drop two inches. The air in the room tastes different. Elena stops holding her breath every time the landlady walks past their door. Marcus can sleep through the night without waking up at three in the morning to mentally balance a ledger that does not balance.
In the data, this translates to soaring success metrics. Debt shrinks. Savings accounts crawl out of the negative integers. Families buy vegetables with crisp skins instead of bruised clearance items. They patch the hole in the roof before the autumn rains turn the drywall to mush. The quantitative metrics glow with health. The spreadsheets of the economists back at the university look pristine.
Yet, numbers are notoriously blind to the human soul.
Money is never just an exchange medium. It is an emotional currency loaded with history, shame, power, and identity. When you impose an external spending plan onto a couple already navigating the delicate power dynamics of a shared life, you introduce an invisible third party into the bedroom, the kitchen, and the argument.
The budget becomes a moral scorecard.
Suppose the spending plan dictates that every single dollar must be allocated toward debt reduction, housing stability, and nutritional staples. Every line item is justified. Every luxury is audited. On paper, this is disciplined. In human reality, it is a straitjacket.
Picture Elena standing in the aisle of a corner store after a crushing twelve-hour shift. She is exhausted. Her feet throb inside shoes that lost their soles six months ago. She spots a small, overpriced bouquet of yellow roses or a simple pastry she used to love before every grocery trip became a military campaign. Under the strict terms of the assigned spending plan, those flowers are a deviation. They are a breach of contract. They represent failure.
When she brings them home, Marcus does not see a simple act of self-soothing. He sees a threat to their stability score. He sees the spreadsheet cracking. A quiet tension settles over the kitchen table. It is not about the ten dollars spent on roses; it is about the suffocating realization that even when they finally have money, they still do not own their choices.
This is where the good results curdle into the bad.
Cash programs that come pre-packaged with paternalistic budgeting mandates often substitute one form of scarcity for another. Financial scarcity gives way to behavioral surveillance. Couples find themselves performing poverty correctly for the evaluators. They learn to report what the planners want to hear, hiding the small, messy human expenditures that make endurance bearable. A pizza ordered on a night when both adults are too shattered to cook becomes a guilty secret whispered between partners. The cash was supposed to liberate them, but the accompanying plan reminds them that they are still viewed as incompetent children needing adult supervision.
Behavioral economists talk endlessly about cognitive bandwidth. When you are poor, your brain is consumed by the sheer computational load of survival. Every decision is a high-stakes calculus. Cash transfers successfully expand that bandwidth. They give people the cognitive breathing room to look up from the dirt and see the horizon.
However, rigid spending plans can paradoxically constrict that newly won freedom. Instead of worrying about whether the electricity will stay on, the couple now worries about whether their spending habits match the bureaucratic ideal of financial literacy. The anxiety simply changes shape. It mutates from material dread into psychological compliance.
To understand why some couples thrive under these combined regimes while others fracture, we have to look at the fault lines of domestic power.
Money is power. In relationships already strained by economic inequality, who controls the spreadsheet often controls the narrative of the household. If Marcus earns more, or if Elena is designated as the primary account manager for the grant funds, subtle dynamics of accountability emerge. "Why did you spend that?" becomes a loaded weapon. The cash infusion, intended to build a bridge toward a shared future, can inadvertently expose existing cracks in trust and communication.
Some couples use the structure as a sacred scaffolding. They sit down together every Sunday evening, not with teeth clenched in fear, but with coffee mugs in hand, treating the spending plan as a collaborative board game where they are finally winning against the house. For them, the rules provide safety rails. They agree on goals—a reliable used car, a security deposit for a safer neighborhood, a modest buffer fund—and every line item on the spreadsheet is a mutual brick laid toward a shared castle.
For other couples, the plan is a foreign language forced upon them by well-meaning strangers who have never known what it is like to pawn a wedding ring just to pay for an emergency root canal. For them, the rules feel arbitrary, punishing, and detached from the chaotic reality of their daily survival. When an unexpected crisis strikes—a sick child, a towing fee, a uniform requirement for a new job—and the rigid spending plan forbids shifting funds to cover it, the system breaks down. The couple is forced to choose between breaking the rules and letting the emergency swallow them whole. Choosing survival over the spreadsheet brings an acute sense of guilt, as if they have failed a test they never asked to take.
We live in a culture obsessed with silver bullets. We want social interventions to be clean, measurable, and easily scalable. We want to press a button labeled cash plus education and watch self-actualizing, perfectly optimized citizens emerge on the other side.
Humanity refuses to cooperate with this neat engineering.
People are messy, contradictory, and stubbornly attached to their autonomy. They do not just want to survive; they want agency. They want the dignity of making their own mistakes, of buying the wrong thing sometimes, of experiencing the immediate consequence of a poor choice without an invisible auditor wagging a finger from a university research paper.
The data from these experiments tells a nuanced story that policymakers often struggle to digest. Unconditional cash—cash given with zero strings attached, zero spending plans, and zero moral lectures—consistently outperforms conditional or heavily managed cash. When you trust people, they tend to surprise you. They pay off high-interest debt. They invest in their kids. They buy tools to earn more money. They do this not because a binder told them to, but because dignity is a powerful motivator.
When you add the strings, when you wrap the cash in a bureaucratic blueprint, you achieve compliance at the cost of trust. You fix the balance sheet while bruising the human spirit.
Imagine Elena and Marcus again, sitting at that scarred wooden kitchen table after the children have finally fallen asleep. The bills are paid for the month. The ledger is balanced. The grants officers looking at their charts would mark this household as an unmitigated success story.
Yet, Marcus is staring out the dark window, wondering if he is valued for his labor or his compliance. Elena is folding a worn-out shirt, wondering when they will be allowed to buy something simply because it brings them joy instead of utility.
The cash saved them from the immediate cliff. But the plan reminded them of the walls.
As we rethink how we support those weathering the storms of economic instability, we must confront an uncomfortable truth. True help is not just about moving numbers from one column to another. It is about restoring the fundamental right to choose, to fail, to adapt, and to breathe without someone else holding the stopwatch.
Until we trust people with the full weight of their own freedom, every financial rescue will carry an invisible tax, payable in the currency of human dignity.