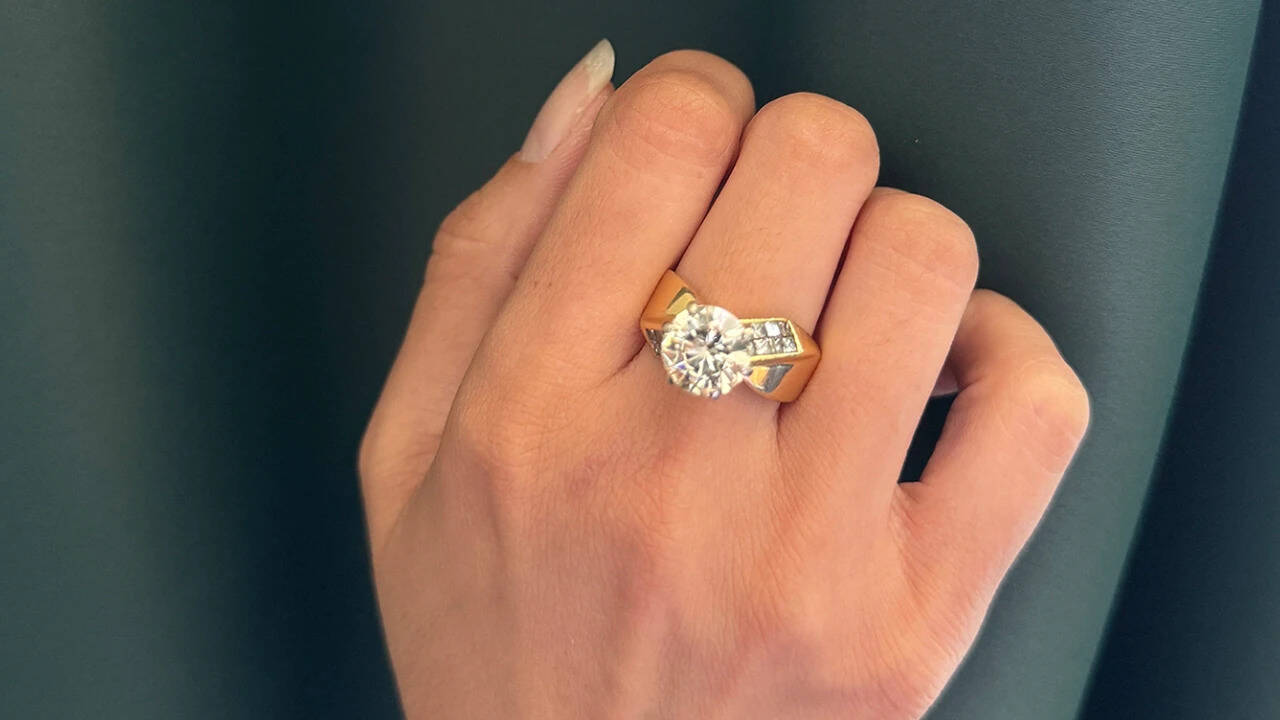
Extreme valuation gaps in secondary markets—such as a £5 purchase of an item later appraised at £15,000—are not random strokes of luck; they are predictable outcomes of severe information asymmetry, compressed seller time horizons, and uncalibrated appraisal channels. To understand how a £3,000-to-one price-to-value multiple occurs in an informal venue like a UK car boot sale, this analysis maps the underlying market mechanics into four structural components: the Pricing Divergence Framework, Seller Liquidity and Cost Functions, Verification Friction and Signal Degradation, and an Operational Buyer Protocol. Because no underlying article text or source records are supplied in the prompt, specific transaction facts are treated as structural hypotheses rather than verified historical events, while the economic and gemological mechanisms governing such discrepancies are examined rigorously.
The Pricing Divergence Framework
Headline stories about five-pound diamond rings treat the event as an anomaly of fate. In market microstructure terms, the gap between transaction price and intrinsic or market appraisal value is a function of three variables: information asymmetry, channel mismatch, and valuation regime.
A car boot sale operates as a high-throughput, low-cost clearinghouse designed to convert household clutter into immediate cash. Sellers set prices using heuristic anchors—round numbers, perceived novelty, or bulk-clearance urgency—rather than formal asset pricing models. A buyer who recognizes gemological or metallurgical indicators possesses private information that the seller lacks or chooses not to price. Even when a seller suspects an item might be valuable, the cost of proving that value on grass at 6:30 AM exceeds the seller's willingness to invest time.
Channel mismatch compounds this gap. A £15,000 valuation figure in media accounts typically reflects either an insurance replacement valuation, a retail appraisal, or a specialist auction estimate (inclusive of buyer premiums and curated provenance). A car boot sale is a hyper-local cash market with zero authentication infrastructure, no escrow, and minimal repeat-reputation enforcement. Comparing a cash clearing price at a field sale to a formal retail or insurance valuation conflates two distinct markets with incompatible liquidity profiles and transaction costs.
The third driver is valuation regime ambiguity. A diamond ring's economic value is not a single scalar number. Retail replacement value includes overhead, marketing margins, and VAT or retail markups; auction hammer value reflects competing bidder demand on a specific day; scrap precious-metal value sets a floor based on weight and fineness; and private-sale realization reflects search friction and negotiation discounts. Treating a single headline figure as liquid cash in hand overstates immediate realizable value whenever resale channels carry steep commissions, testing fees, or long holding periods.
Seller Liquidity and Cost Functions
To see why a seller prices an item at £5 rather than £500 or £5,000, model the seller's decision through a basic cost-and-time trade-off. A typical car boot seller faces fixed pitch fees, early-morning travel, weather exposure, and a finite window before buyers depart or rain sets in. Every minute spent negotiating over a single item carries an opportunity cost across dozens of other items on the table.
From the seller's perspective, low-denomination pricing functions as a throughput accelerator. When an item is unverified—missing hallmarks, faded stamps, or covered in grime—the seller faces a choice between holding the item for specialized appraisal (which requires time, travel, transport risk, and potentially paid testing) or liquidating it immediately for marginal cash. When a seller's liquidity preference is high and their verification capability is low, reservation prices collapse toward nominal pocket-change thresholds.
The second limitation in standard narratives is ignoring the risk-adjusted return of verification. Suppose a seller has a ring that might be worth £200 or might be worth £15,000, with a high probability that it is costume jewelry or low-grade synthetic stone worth £2. Traveling to a jeweler or gemological lab imposes certain time and potential fee costs against an uncertain payoff. Rational or time-constrained sellers frequently exit early at a small certain gain rather than pay upfront friction for an uncertain upside, especially when they lack diagnostic tools.
This dynamic also explains why sellers often misread surface cues. Tarnish on silver, heavy wear on a band, or an unremarkable setting can mask precious metal or genuine stone, while flashy costume pieces can mimic luxury aesthetics. Without a loupe, an electronic tester, or hallmark literacy, visual inspection at arm's length compresses price dispersion toward the low end.
Verification Friction and Signal Degradation
High-value items lose pricing signals rapidly when moved out of formal supply chains. In an established jewelry transaction, value is anchored by hallmarks, certifications, provenance records, and standardized grading. At an informal outdoor market, each of these signals degrades.
Hallmarks are designed to certify precious metal fineness, yet they can be worn down by decades of resizing or polishing, obscured by dirt, located inside tight shanks, or misread without magnification. Even a legitimate hallmark does not automatically grade a center stone; natural diamonds, simulants such as cubic zirconia or moissanite, and lab-grown stones require optical, thermal, or spectroscopic inspection that cannot be reliably performed in a crowded field. Setting quality—such as prong construction, gallery finishing, and stone seating—provides clues, but skilled imitations narrow visual differentiation for casual observers.
A price anomaly persists only as long as the cost of closing the information gap exceeds the expected gain from doing so within the transaction window.
This creates a bottleneck on both sides of the deal. Buyers face the risk of adverse selection in reverse: if they overpay assuming every sparkling stone is a diamond, their portfolio fills with glass and paste. Conversely, sellers face lemon-market discounting: because buyers cannot verify quality on the spot, buyers discount offers across the board to protect against fakes. When a seller sets a flat £5 price, the transaction clears precisely because the buyer's downside risk is capped at £5 while the upside—if genuine—is asymmetric.
The mechanism also highlights a crucial distinction between paper valuation and net realizable cash. Even after acquiring a genuine piece at a steep discount, converting it into cash requires navigating secondary channels: pawn shops (fast liquidity, steep discount), auction houses (broader buyer pool, commission fees, cataloguing delays, potential reserve risk), or private buyers (higher potential net proceeds, higher search and security friction).
Operational Buyer Protocol
Anyone approaching informal secondary markets for high-upside finds should treat the activity as disciplined sourcing under uncertainty rather than treasure hunting. The operational sequence below structures risk control without pretending certainty exists in unverified environments.
- Establish a hard loss cap before engaging. Define the maximum cash outlay per unverified item based on worst-case zero-intrinsic-value loss. If a £5 or £20 loss is immaterial to your budget, you can tolerate high false-positive rates; if a small loss stings, walk away from unverified high-ticket guesses.
- Inspect physical and structural signals systematically. Look closely at wear patterns, solder joints, hallmark impressions, and stone settings rather than relying on overall shine. Note whether stones are prong-set or glued, check for backing or foil behind stones, and observe how light refracts and disperses without assuming visual brilliance proves diamond origin.
- Price in post-purchase verification and exit costs. Factor in the cost and time of independent gemological testing, cleaning, or repair, plus the fee structure and timeline of your intended exit channel. A theoretical appraisal figure is not cash until fees, taxes, and market discounts are accounted for.
- Maintain strict negotiation discipline and personal safety. Keep interactions brief, polite, and transparent without inflating claims or creating friction. Conduct transactions in open, public environments, avoid carrying excessive cash unnecessarily, and never treat an unverified outdoor purchase as an insured asset until qualified inspection confirms what you hold.
- Track hit rates and net realized margins. Record acquisition price, testing costs, holding period, and net sale proceeds across all finds. Measuring actual realized return prevents confirmation bias, where one dramatic win obscures dozens of low-value or break-even purchases.
Methodological Limits and Market Outlook
No sourcing framework eliminates false positives or guarantees windfalls. Informal markets are noisy, supply is erratic, and convincing imitations—including high-grade simulants and lab-grown stones—continuously raise the technical bar for field evaluation. Furthermore, widespread access to online resale guides and mobile search tools has gradually narrowed obvious pricing gaps among more connected sellers, though time pressure and physical inspection limits still generate mispricings.
Looking ahead, secondary markets will likely split further between data-assisted micro-arbitrage and certified specialist trading. As everyday sellers use quick visual lookups for recognizable brands, mispricings increasingly concentrate in items where physical inspection, metallurgical nuance, or unbranded gemological quality matters more than a brand name—and where disciplined risk management separates repeatable practice from wishful thinking.